The Science
of Alpha.
We apply the rigor of the scientific method to financial markets. We are physicists, mathematicians, and statisticians decoding the complex behavior of the global economy.
// Stochastic Volatility Model
dSt = μStdt + √vtStdW1t
dvt = κ(θ - vt)dt + σ√vtdW2t
A signal is replayed before it is trusted.
The historical store is measured in petabytes.
The Research Cycle
Our researchers don't just "find patterns." They build robust theories about market mechanics and test them to destruction.
1. Hypothesis
Ideas originate from academic literature, market observation, or alternative data anomalies. We encourage intuition, but demand proof.
2. Simulation
We replay the strategy against petabytes of historical data using our proprietary "Gauntlet" engine. We account for fees, slippage, and market impact.
3. Production
Once a model passes peer review, it is deployed to our live trading infrastructure. But the work isn't done; we constantly monitor for alpha decay.
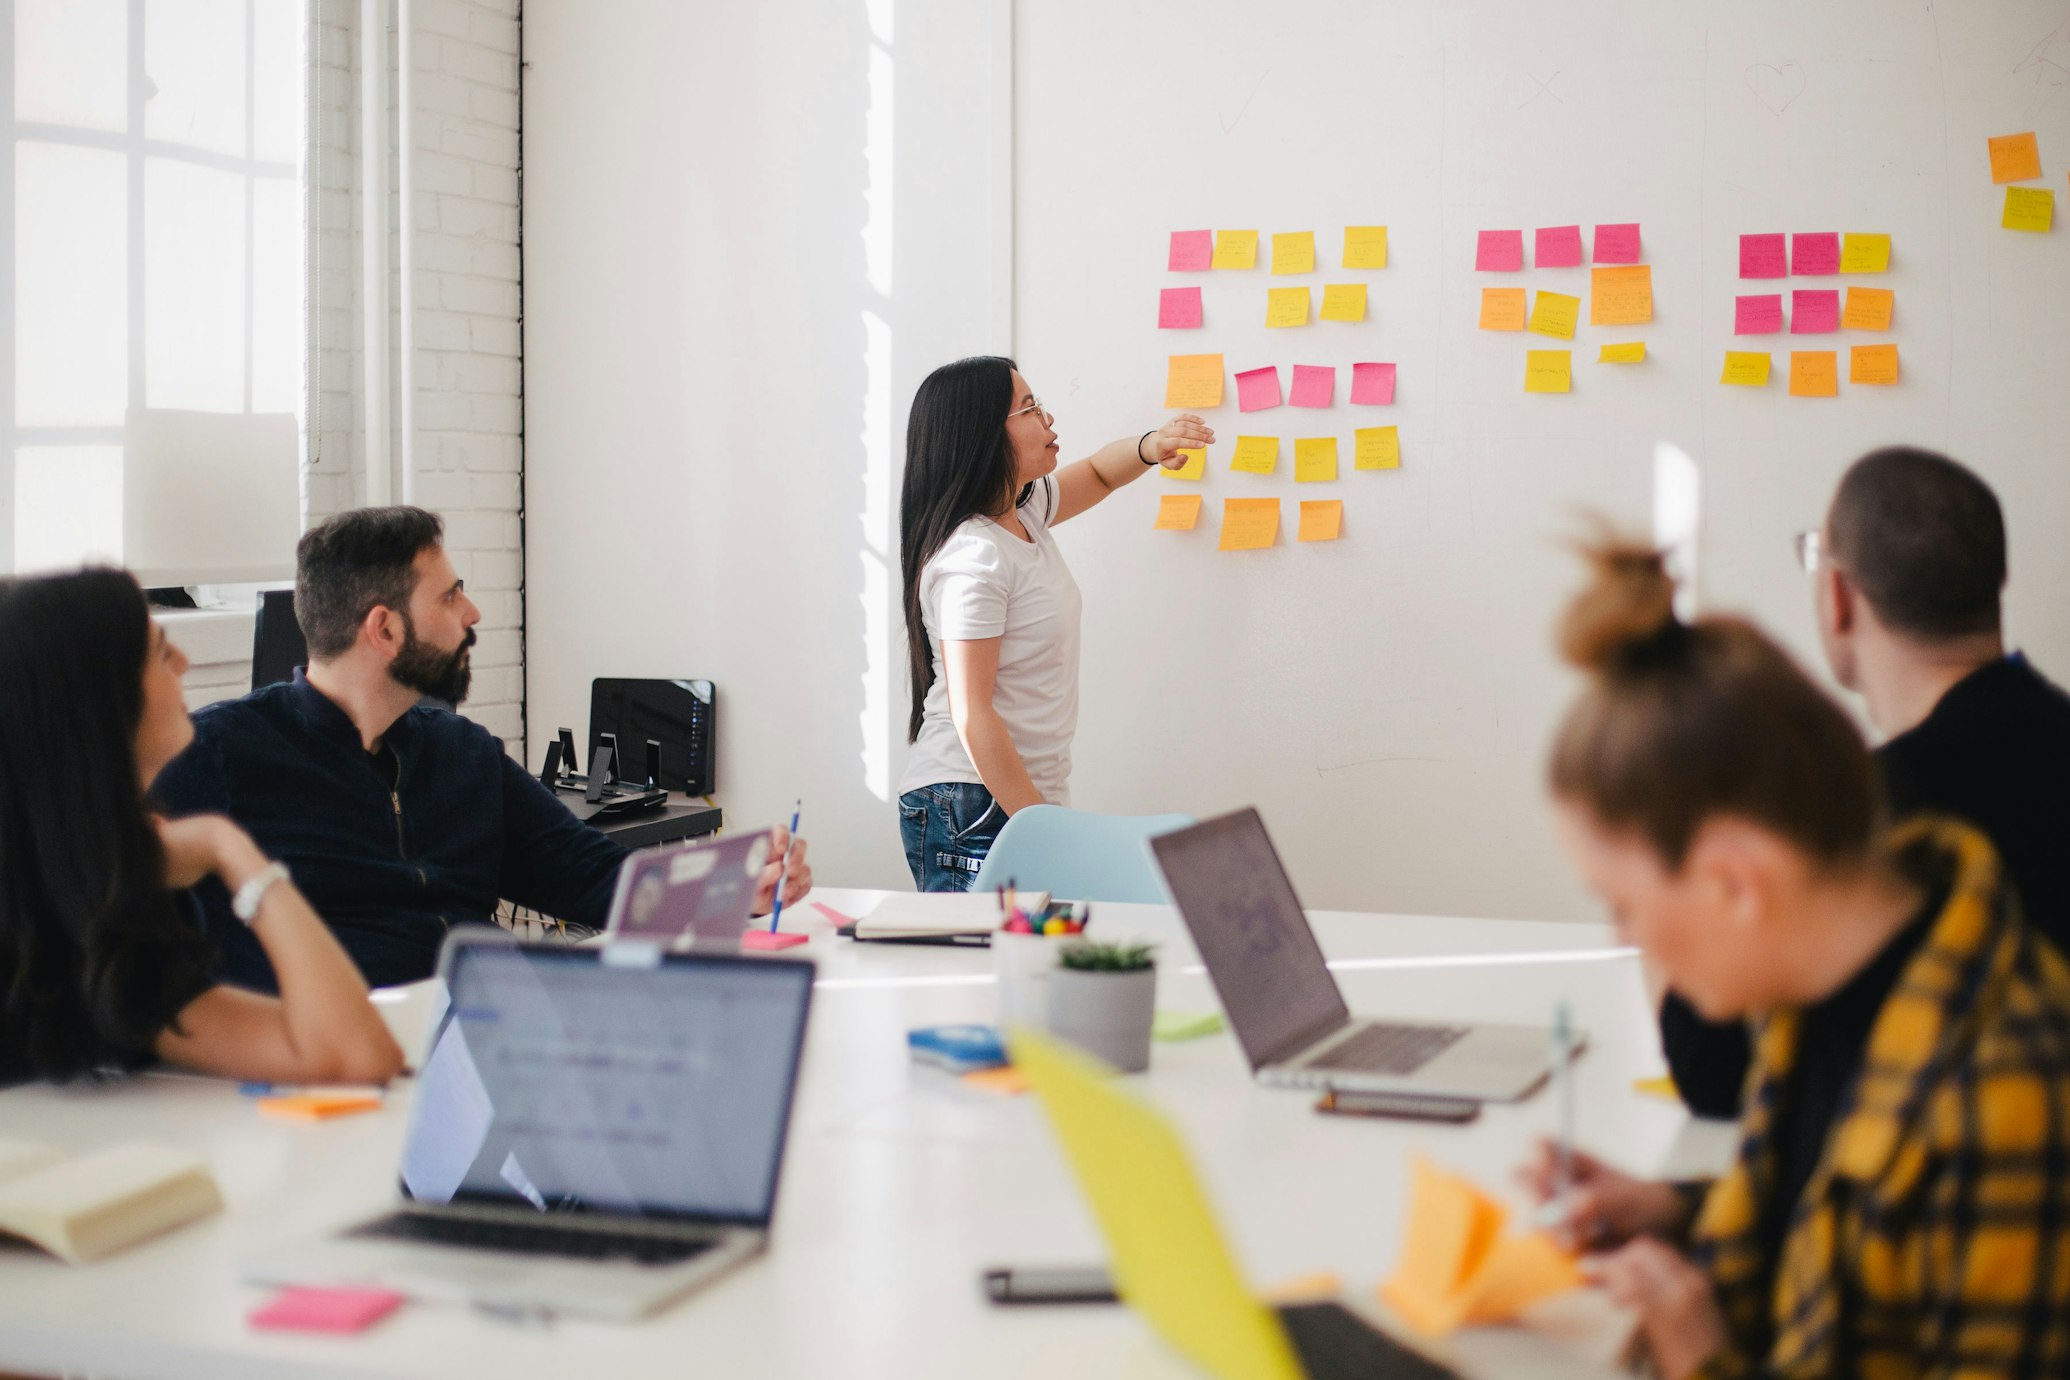
A University Campus,
With Capital.
We have deliberately cultivated an academic culture. We don't have "traders" shouting across a floor. We have quiet, collaborative spaces where researchers solve hard problems together.
Internal Journals
We publish our own internal research papers. Knowledge is shared, not siloed.
Collaborative Codebase
Our research library is a shared resource. You stand on the shoulders of giants.
Whiteboards Everywhere
Walk through our office and you'll see equations scrawled on glass walls, napkins, and desks.
Voices from the Lab
"A signal is replayed before it is trusted. Most ideas die in that replay."
"The data here is cleaner than anything we saw in academia. The engineering team treats data as a first-class citizen, which lets us focus on the modeling, not the munging."
"The work stays with the firm. A signal is replayed before it is trusted."
Solve the Unsolvable.
We are looking for researchers who aren't afraid of hard problems.